
6 Investment Business Ideas in India: Costs, Pay, Licenses
Sebi just made it cheaper to become a licensed investment advisor in India. Here's what six different investment businesses actually cost to start, license, and earn.
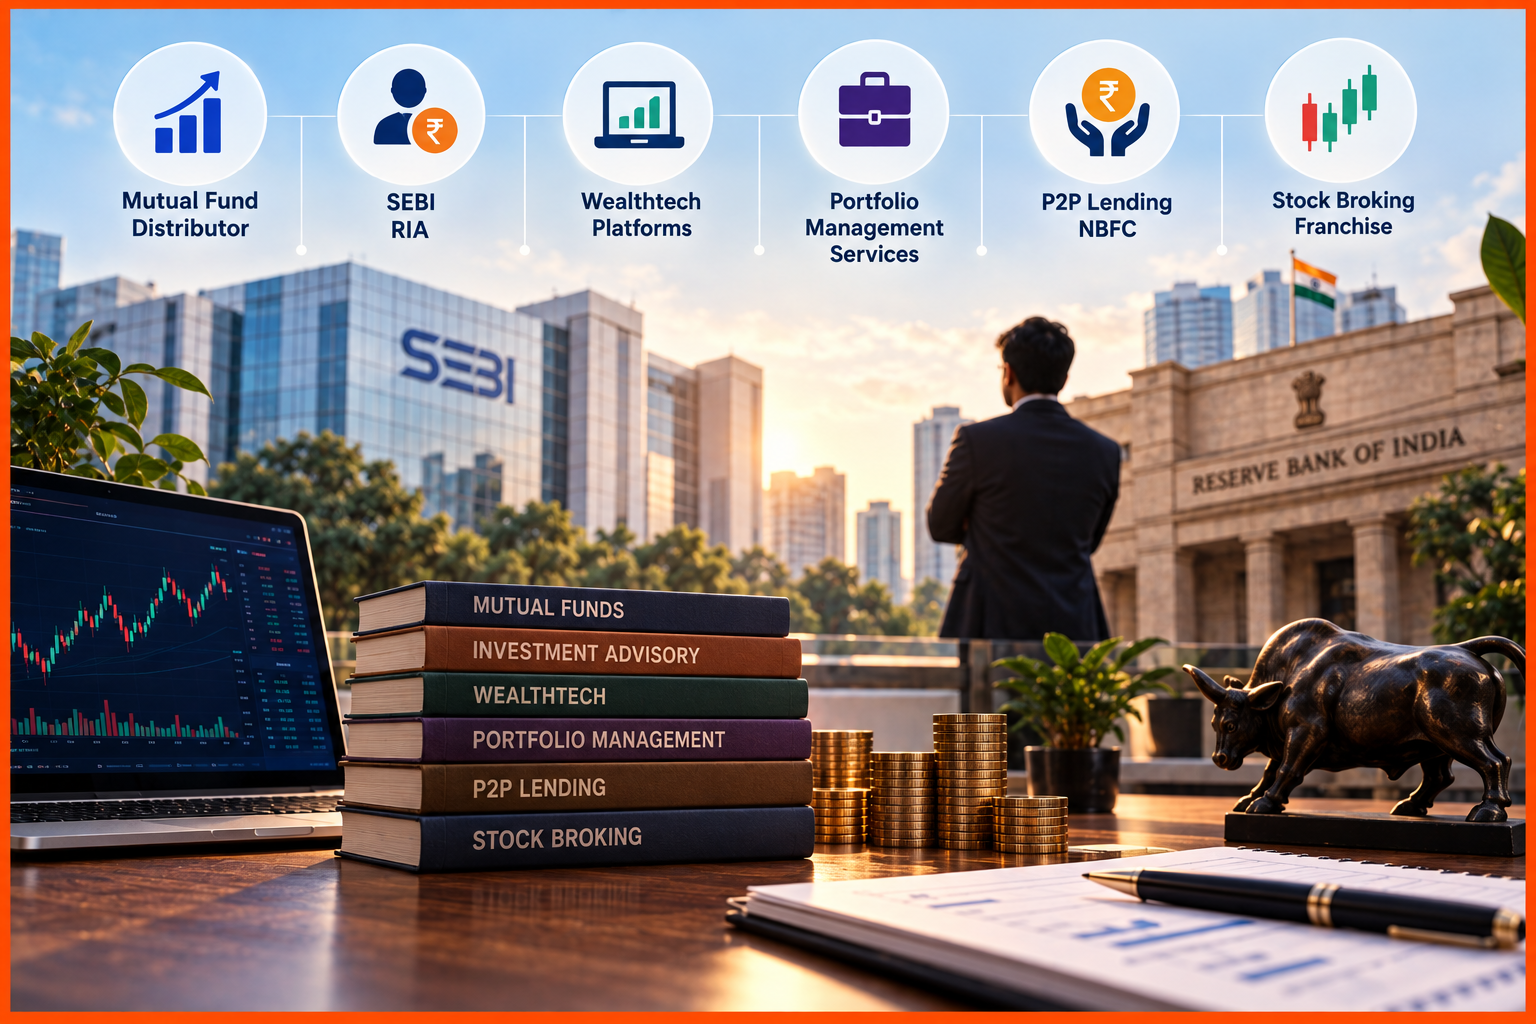
In December 2024, Sebi quietly made it far cheaper to become a licensed investment advisor in India. It scrapped the old ₹5 lakh net worth requirement for individual advisors and replaced it with a graded deposit as low as ₹1 lakh, tied to how many clients you take on. That one regulatory change reset the economics of six different investment businesses you can legally start in India right now, from a mutual fund distributorship that needs no net worth at all, to a portfolio management service that still demands ₹5 crore just to register. Here's what each one actually costs to start, which regulator it answers to, and what it realistically pays.
| Business | Regulator / License | Capital or Net Worth Needed | Realistic Earning Ceiling |
|---|---|---|---|
| Mutual Fund Distributor | AMFI ARN, under Sebi | ₹3,000 + GST ARN fee, no net worth floor | ~₹1L/month needs ₹10-12cr AUM, 3-5 years to build |
| Sebi Registered Investment Advisor | Sebi (Investment Advisers Regs) | ₹1-10L graded deposit (individual) | 2.5% of assets under advice/year, or ₹75,000/family/year flat |
| Wealthtech / robo-advisory platform | Sebi (as RIA/MFD) plus tech build | No fixed floor, but real product cost | Groww: $142M+ raised, 10M+ users. Kuvera: ~$1.97B AUM before its 2024 CRED acquisition |
| Portfolio Management Service | Sebi (Portfolio Managers Regs) | ₹5 crore provider net worth | Fee on AUM; ₹50L minimum client ticket size |
| P2P Lending NBFC | RBI (NBFC-P2P) | ₹2 crore net owned fund | Spread-based; leverage capped at 2x |
| Stock broking franchise (Authorised Person) | Exchange-registered via a broker | ₹41,000-71,000 setup + ₹30-60k/month opex | 20-40% revenue share, scales with client referrals |
Mutual Fund Distributor: The Lowest Real Barrier
This is the cheapest legitimate entry point into India's investment industry. Clear the NISM-Series-V-A exam, complete the Know Your Distributor process, and pay a ₹3,000 (plus 18% GST) ARN fee to AMFI, and you can legally sell mutual funds under your own distributor code, competing for the same customers as the mutual fund apps that dominate the retail market. Sebi banned upfront commissions years ago, so the entire income is trail commission, paid daily on assets under management at roughly 0.20% to 1.00% a year. To clear ₹1 lakh a month you need somewhere around ₹10-12 crore in equity-heavy AUM at a blended 1% trail rate, which realistically takes 3 to 5 years of steady SIP onboarding and client retention.
Verdict: start here if you have an existing network of people who trust you with money and you're willing to wait years for trail income to compound. Don't start here if you want fast cash.
Sebi RIA: The Fee-Only Route That Just Got Cheaper
An RIA gets paid to advise, not to sell product, which is the opposite incentive structure from an MFD. You need a graduate degree and to clear NISM-X-A and X-B, and since Sebi's December 2024 amendment, individuals post a graded deposit of ₹1 lakh to ₹10 lakh depending on client count, instead of the old ₹5 lakh net worth test. Registration itself costs a flat ₹2,000 to Sebi. Revenue comes from client fees: either 2.5% of assets under advice per year, or a flat ₹75,000 per family per year, whichever model you choose.
Verdict: the better business if you actually want to give advice rather than push product, and the entry cost just dropped by roughly 80% for a solo advisor. The catch is that fee-only clients are a harder sell than commission-hidden ones; you have to justify the fee out loud.
Wealthtech Platforms: Groww Proved the Algorithm Isn't the Product
This is the highest-ceiling, highest-effort option on this list, and the most instructive failure-then-pivot story in Indian fintech sits inside it. Groww launched in 2017 as a pure robo-advisor, an algorithm managing client money automatically. Indian investors didn't trust it. Groww pivoted to a simple, direct-mutual-fund investment app instead, and by 2024 it was adding more than 6 million users a year and capturing 40% of all new NSE demat accounts. Kuvera took a different route, going zero-fee on direct mutual funds and building to roughly $1.97 billion in AUM before CRED acquired it in 2024. INDmoney, founded by Ashish Kashyap in 2019, raised over $200 million building a single dashboard across stocks, mutual funds, fixed deposits and US equities.
None of the three winners built what they originally pitched.
The product that worked was distribution and trust, not the advisory algorithm.
Verdict: only start here if you're building a product business, not a licensing business, you're competing with companies that have raised nine figures, and the algorithm is rarely the moat.
Portfolio Management Services: The ₹5 Crore Floor
PMS is where retail-scale ideas stop working. Only companies or LLPs can register as a Portfolio Manager, the entity needs a chartered-accountant-verified net worth of ₹5 crore, and the Principal Officer needs five-plus years of investment management experience plus an MBA, CA, CFA or CS. You'll also need an independent custodian and a compliance officer before you take a single client. On the client side, Sebi has required a minimum ₹50 lakh investment since January 2020, so this is a high-net-worth business by design, not a mass-market one.
Verdict: not a first business. This is what an established RIA or fund manager graduates into once they already have institutional-grade infrastructure and a wealthy client base.
P2P Lending NBFC: RBI's Territory, Not Sebi's
Peer-to-peer lending sits under the RBI, not Sebi, as an NBFC-P2P. You need a net owned fund of ₹2 crore before the Certificate of Registration is even issued, a leverage ratio capped at 2, and a real India-based office with management based here too. Existing NBFCs are barred from converting into NBFC-P2P entities, and the platform can never touch customer funds directly, everything runs through an escrow structure. Income comes from the spread and platform fees, not commission.
Verdict: the most operationally heavy option here, closer to running a small NBFC than a financial services shopfront. Worth it only if you have real underwriting expertise, not just a lending app idea.
Stock Broking Franchise: The Crowded But Fastest Start
Becoming an Authorised Person under an existing broker like Zerodha or Angel One is the fastest of the six to actually open for business. Zerodha's setup runs ₹41,000 to ₹71,000, plus an ₹11,000 one-time exchange charge and ₹30,000 to ₹60,000 a month in running costs. Revenue share climbs with volume: 20% of brokerage on your first 500 referrals, 30% up to 1,000, and 40% beyond that. The honest catch is competition: Zerodha alone already runs more than 5,000 such partners, so you're not filling a gap, you're competing for the same client pool as thousands of existing franchisees.
Verdict: fastest to launch, lowest capital of the "real business" tier, but the market is genuinely saturated. Works best if you already have a specific local client base a national platform can't reach on its own.
Which One Actually Fits You
I'd rule out PMS and the wealthtech-platform route for almost anyone reading this as a first move; one needs ₹5 crore before you start, the other needs venture-scale funding to out-market Groww and INDmoney. For most people with a real network and patience, the RIA route is the one that changed the most in the last year, a deposit as low as ₹1 lakh where ₹5 lakh net worth used to gate you out, and it pays you to be right instead of paying you to sell.
FAQ
Which investment business is cheapest to start in India?
Becoming a mutual fund distributor is the cheapest, requiring only a ₹3,000-plus-GST ARN fee and no net worth requirement, though income builds slowly through trail commissions over several years.
Do you need SEBI registration to give investment advice in India?
Yes. Giving personalised investment advice for a fee requires SEBI Registered Investment Advisor registration, which since December 2024 needs a graded deposit of ₹1 lakh to ₹10 lakh for individuals instead of the earlier ₹5 lakh net worth requirement.
How much capital do you need for a PMS license in India?
SEBI requires a portfolio manager entity to hold a minimum net worth of ₹5 crore, verified by a chartered accountant, and clients must invest at least ₹50 lakh.