
Banking Technology IPOs: How B2B Fintech Companies Can Turn Global Growth Into a Public-Market Opportunity
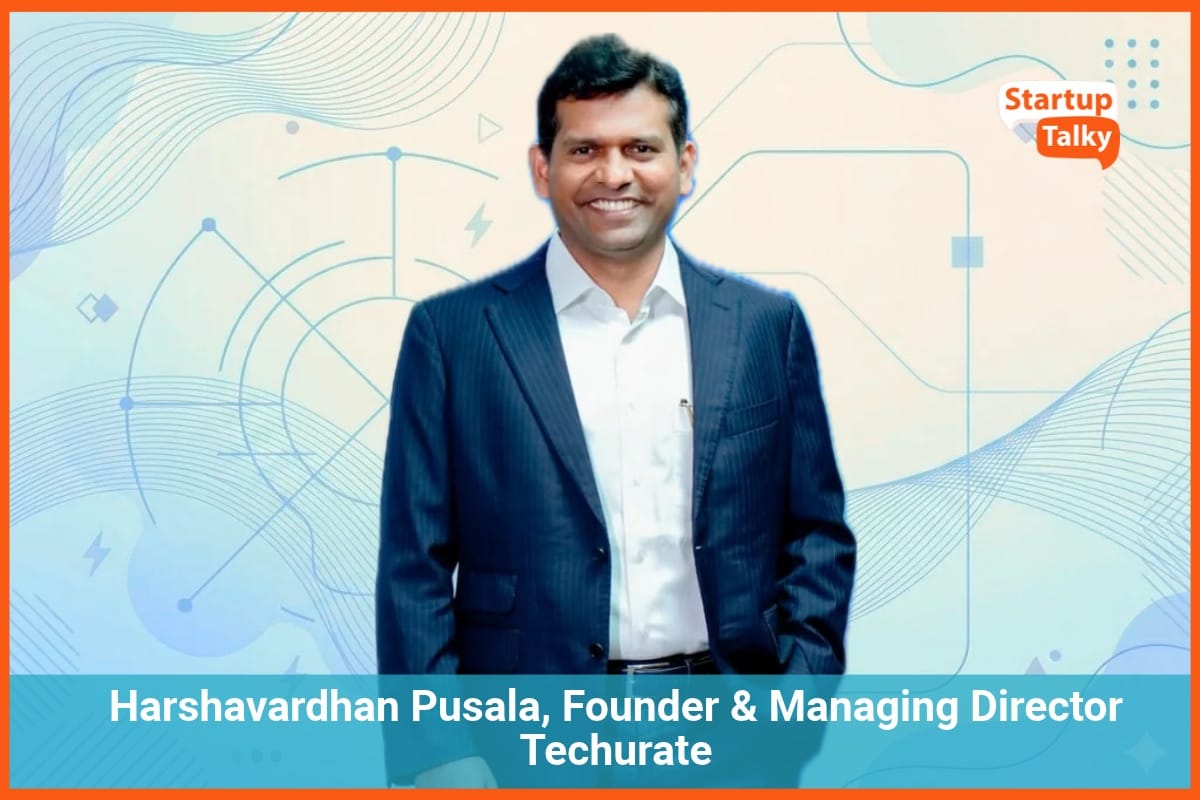
Harshavardhan Pusala, Founder & Managing Director of Techurate, shares insights on IPO readiness, institutional capital, AI-led banking technology, financial governance and choosing the right listing market for global B2B fintech companies.
India’s fintech and banking-technology ecosystem is entering a new phase of institutional growth, creating opportunities for technology companies that can combine strong customer relationships with predictable revenues, robust governance and scalable products. India’s fintech industry was valued at around US$44.1 billion in 2025 and is projected to grow at a 16.6% CAGR through 2030, according to IBEF.
The broader global fintech market is also expected to expand from US$320.81 billion in 2025 to US$652.80 billion by 2030, representing a 15.27% CAGR. At the same time, banking and investment services are expected to increase global IT spending at a 9% CAGR, reaching around US$1.1 trillion by 2029.
In this edition of StartupTalky’s IPO & Secondary Markets Series, Harshavardhan Pusala, Founder & Managing Director of Techurate, shares his perspective on how B2B banking-technology companies can prepare for institutional capital and public markets.
Emerging-Market Revenue Can Become More Investable With Strong Visibility and Diversification
StartupTalky: Techurate works with more than 30 banks across 20+ countries, largely in Africa. How do public-market and institutional investors value revenue from emerging-market bank clients, and what does a company need to show to reduce the perceived currency and concentration risk?
Harshavardhan Pusala: Investors generally look beyond the geography of a customer and examine the quality, durability and diversification of the underlying revenue. Emerging markets can present additional considerations around currency, regulation and concentration, but these risks can be understood and managed when the business has strong institutional customers, repeatable contracts and disciplined financial controls. For a B2B banking-technology company, the important metrics are not simply where revenue originates, but how predictable it is, how long customers stay, how diversified the customer base is and how contracts translate into cash flows.
A company should be able to clearly separate reported revenue from foreign-exchange movements and explain the underlying operating performance. Customer concentration should also be monitored transparently rather than addressed only when an investor asks about it.Ultimately, institutional investors need visibility. Consistent reporting, audited financials, clear contract structures, prudent treasury practices and a diversified customer base help convert an emerging-market exposure from a perceived risk into a measurable business characteristic.
Consistent Revenue Reporting Helps B2B Technology Companies Build Pre-IPO Credibility
StartupTalky: B2B banking-technology companies often have long sales cycles and lumpy contract revenue. How should such a company present its financials, including revenue recognition, order book and recurring revenue, to be taken seriously by pre-IPO investors?
Harshavardhan Pusala: The first principle is consistency. A company should have a clear accounting policy for revenue recognition and apply it consistently across contracts. Investors should be able to understand what has been billed, what has been recognised as revenue, what remains contracted and what is expected to convert in future periods. For businesses with long enterprise sales cycles, order book and pipeline should not be presented interchangeably.
A signed contract, a committed order and an opportunity under discussion represent different levels of certainty. Separating these categories creates credibility. Recurring revenue is equally important, but it needs to be defined carefully. Investors should understand which revenues are genuinely recurring, which are implementation or project revenues, and how existing contracts typically expand or renew. Alongside revenue, management should provide context on gross margins, customer retention, collections and cash conversion. The objective is not to make a lumpy business look like a subscription business. It is to give investors enough consistent information to understand the economics of the business and build confidence in the quality of reported numbers.
Multi-Country Finance and Governance Need to Be Built Before the IPO Process
StartupTalky: Operating across many regulatory regimes adds complexity to accounts, tax and compliance. What finance and governance structures are needed to make a multi-country B2B fintech audit-ready for a listing?
Harshavardhan Pusala: Audit readiness starts well before a company decides to pursue a listing. A multi-country business needs clearly defined financial ownership, standardised reporting processes and strong documentation across entities. At the finance level, this means a robust month-end close process, reconciliations, documented revenue policies, tax compliance, intercompany controls and appropriate foreign-exchange processes.
Management should also have a reliable consolidation framework so that performance across countries can be viewed consistently.Governance is equally important. Clear approval matrices, segregation of duties, internal controls and periodic reviews reduce dependence on individual decision-makers. As the company grows, internal audit or an independent control-review mechanism can identify gaps before they become audit issues. The most important mindset shift is to treat audit readiness as an operating discipline rather than an IPO exercise. If financial information is accurate, traceable and available on time every month, the transition to a more rigorous institutional environment becomes significantly more manageable.
Institutional Capital Should Solve a Defined Growth Requirement
StartupTalky: As founder of a company that has grown from India into international markets, how do you decide when outside institutional capital, including pre-IPO or secondary rounds, is worth the dilution and governance obligations that come with it?
Harshavardhan Pusala: Capital should solve a clearly defined business requirement rather than become a milestone in itself. The question we would ask is what additional capital enables that the existing business cannot achieve at the same pace. For a technology company serving large institutional customers, capital can support product development, geographic expansion, talent, compliance infrastructure or strategic acquisitions.
The potential value of those investments needs to be weighed against dilution, governance requirements and the expectations that come with institutional capital. A secondary transaction also needs to be viewed differently from primary capital because it can provide liquidity to existing shareholders without necessarily increasing the company's operating capital. Both structures need clear objectives. For founders, valuation is only one part of the decision. The quality of the investor, strategic relevance, governance expertise, patience and ability to support the next stage of growth can be equally important. The right capital partner should strengthen the company's institutional capabilities rather than simply add capital to the balance sheet.
AI Valuation Needs to Be Supported by Measurable Business Outcomes
StartupTalky: With TigiOS, you are building AI and automation into core banking. How do investors currently value AI-led product claims in fintech, and what evidence do they need beyond the product narrative?
Harshavardhan Pusala: AI is increasingly becoming part of the technology conversation, but the investment case ultimately has to come back to measurable business outcomes. Simply describing a product as AI-enabled is not enough. Investors should be able to see what the technology actually improves: processing time, operating efficiency, accuracy, risk management, customer experience or the cost of serving an account.
Evidence could include adoption levels, measurable productivity improvements, customer retention, usage patterns and the economics of delivering the product at scale.In banking technology, reliability and governance are particularly important. Institutions need confidence around data security, explainability, controls and integration with existing systems. Therefore, an AI proposition has to demonstrate not only what the technology can do, but how safely and consistently it can operate in a regulated environment. The strongest AI story is ultimately an operating story: technology that creates measurable value and can be deployed repeatedly across customers.
Listing Venue Should Follow the Business Model, Investor Base and Long-Term Strategy
StartupTalky: Where would a company like Techurate choose to list: in India, or in a market closer to its customers? What factors would drive that decision?
Harshavardhan Pusala: A listing venue should follow the company's business, investor base and long-term strategy rather than geography alone. For an internationally focused technology company, the relevant questions would include where its customers and revenues are concentrated, which investor communities understand the business model, regulatory requirements, liquidity, valuation frameworks and the ongoing cost of being a listed company.
India can offer a strong domestic investor ecosystem and familiarity with Indian technology businesses. International markets may provide access to investors who have greater exposure to global B2B software, banking technology or emerging-market businesses. However, a broader investor pool also brings additional reporting and governance expectations. The decision would therefore need to be made closer to the point of readiness, based on the company's scale, revenue mix, governance maturity and strategic priorities at that time. It is less about choosing a location early and more about building a business that can meet the standards of whichever market is ultimately appropriate.
FP&A, Treasury and Internal Controls Need to Mature Ahead of an IPO
StartupTalky: What finance-function capabilities, such as FP&A, treasury and internal audit, do you think founder-led B2B tech companies most often neglect until an IPO forces the issue?
Harshavardhan Pusala: The most common gap is often not accounting itself, but the broader finance function's ability to support decision-making. Founders can remain deeply involved in financial decisions while the company is smaller, but scale requires systems that provide visibility without depending on one or two individuals. FP&A becomes important as soon as a company operates across products or geographies. Management needs reliable forecasts, scenario planning, unit economics and variance analysis.
Treasury also becomes more important for businesses operating across currencies, because cash management and foreign-exchange exposure can materially affect outcomes. Internal controls and internal audit are another area that can receive attention too late. A company should progressively build approval controls, access controls, reconciliations and independent reviews as complexity increases.The broader lesson is that the finance function should evolve ahead of the funding stage. An IPO should not be the event that creates financial discipline; ideally, the discipline already exists, and the IPO simply requires it to operate at a higher level of rigour.
 Apoorva Bajj