
IPO Readiness for Indian Startups: How Growing Businesses Can Turn Public Listing Into a Long-Term Growth Opportunity
Vinayak Burman, Founder & Managing Partner, VERTICES PARTNERS, shares key legal and governance lessons for startups preparing for an IPO, covering cap tables, investor rights, reverse flips, ESOPs and founder control.
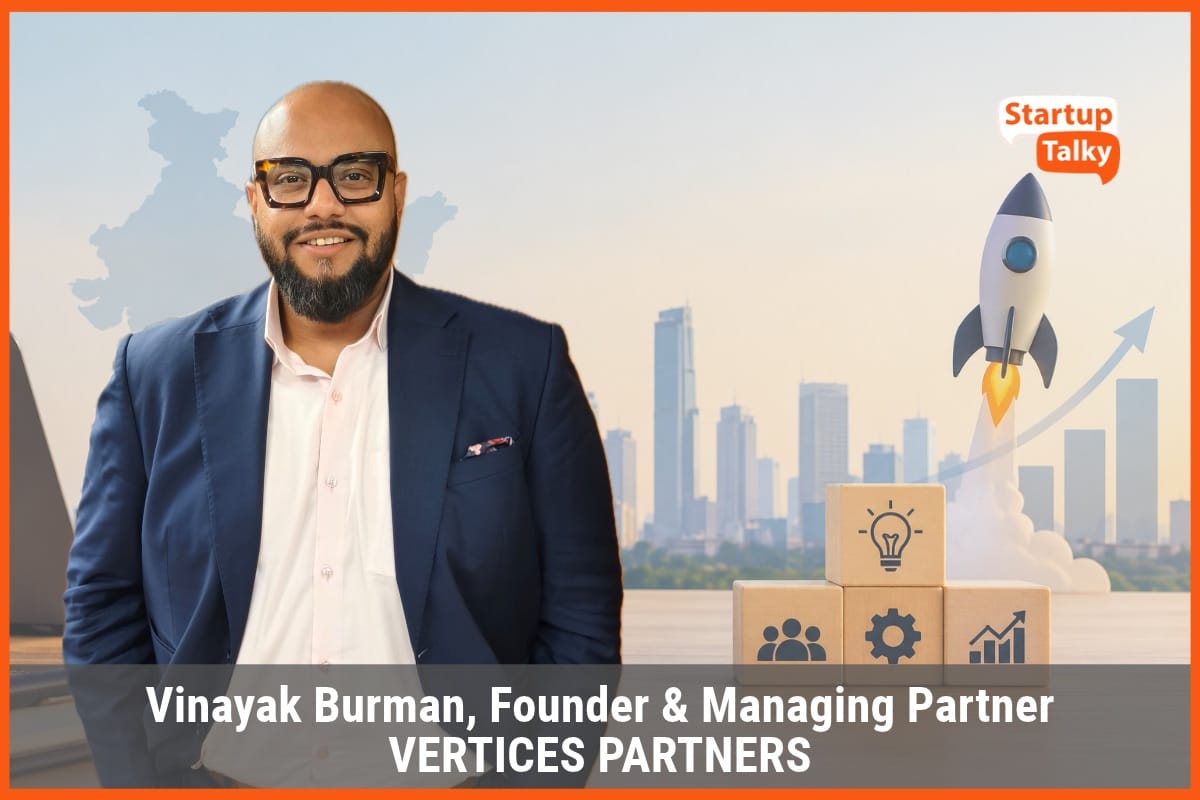
This article has been contributed by Mr. Vinayak Burman, Founder & Managing Partner, VERTICES PARTNERS
India’s capital markets are entering a strong growth phase, creating a larger pipeline of companies preparing for public listings. India’s capital markets revenue pool is projected to grow at a 16% CAGR between FY26 and FY30, driven by rising household financialisation, deeper equity participation and expanding investment products.
The IPO market is also showing strong momentum. India recorded 126 IPOs in FY26, which raised around ₹1,78,963 crore, while 104 mainboard IPOs had already raised approximately ₹1,55,005 crore by October 2026. At the same time, PE/VC-backed IPO activity continues to expand, with 290 such IPOs recorded since 2016, nearly 75% of which took place since 2021.
In this interview, Vinayak Burman, Founder & Managing Partner, VERTICES PARTNERS, shares his perspective on the legal and structural challenges founders should address well before an IPO. He discusses everything from cleaning up cap tables and investor rights to reverse flips, ESOP liquidity programmes, public-company governance and the personal transition founders experience when giving up a degree of control. Pasted markdown(20261103-051800)
Early-stage documentation can create major IPO challenges
StartupTalky: You have advised founders for over two decades, many through fundraising and strategic transactions. When a startup begins preparing for an IPO, which legal or structural issues from early funding rounds, such as shareholder agreements, special rights or messy cap tables, most commonly come back to cause problems?
Vinayak Burman: The challenges that arise when a company prepares to go public are rarely created at the IPO stage itself. More often, they are a consequence of decisions, documentation gaps and informal arrangements that have accumulated over the company’s earlier stages of growth. Some of the recurring issues we encounter include incomplete or inconsistent capitalization tables, unrecorded or inadequately documented transfers, investor rights that have not been formally terminated or appropriately transitioned, and issuances of securities without complete supporting documentation. These matters can become particularly challenging when the company is required to establish a clean and definitive record as part of its public-market preparation.
It is equally important to undertake a detailed review of corporate governance issues, historical capital evolution, shareholder and investor rights, including veto and consent rights, voting arrangements in relation to nominated directors, liquidation preferences and anti-dilution protections, and to assess whether and to what extent such rights remain enforceable or are required to be extinguished or appropriately addressed in the context of a public company.
Similarly, historical ESOP documentation, grants and exercises, as well as the contractual and commercial relationships among founders, investors, employees and other stakeholders, require careful scrutiny. These issues may appear manageable individually, but can become significant when viewed collectively at the time of an IPO.
The lesson is fairly straightforward: IPO readiness begins well before the IPO. Companies should maintain institutional-quality, startup-stage documentation and governance discipline from their first institutional fundraise and throughout subsequent financing rounds. Attempting to reconstruct or remediate ten years of historical records at the time of an IPO is invariably more complex, time-consuming and costly than ensuring that the legal and corporate architecture is properly documented at each stage of the company’s growth.
Investor rights need clear exit and termination mechanisms
StartupTalky: Investor special rights like affirmative voting, board nomination and anti-dilution protections have to be unwound before listing. How difficult are those conversations in practice, and how should founders negotiate early term sheets knowing an IPO may be the eventual exit?
Vinayak Burman: These conversations can certainly be difficult, particularly where investors have negotiated strong rights as part of an early-stage investment. However, the difficulty is usually not in identifying the rights that need to be addressed; it is in managing the expectations created when those rights were originally negotiated.
The key is to think about the eventual exit at the time the rights are being negotiated. Founders should avoid creating rights that are capable of becoming structurally incompatible with a public-company framework. Affirmative voting or veto rights, extensive board nomination rights, preferential economic rights, and anti-dilution protections should include termination provisions linked to a qualified IPO, listing or other specified liquidity event.
From a founder’s perspective, the lesson is to negotiate with the holistic lifecycle of the company in mind. A term sheet should not only answer the question, “What protection does the investor need today?” but also, “What happens to that protection when the company raises a subsequent round, undertakes a strategic transaction or ultimately goes public?” Clear sunset mechanisms and objective triggers negotiated upfront can significantly reduce friction at the time of an IPO and seamless listing of its securities.
Ultimately, good transaction structuring is not about eliminating investor protections; it is about ensuring that those protections have a clearly defined lifecycle and do not become an impediment to the company’s future financing or exit options.
Reverse flips require extensive legal, tax and regulatory planning
StartupTalky: Many Indian startups that set up holding companies overseas are now re-domiciling to India ahead of a listing. What legal and tax realities should founders understand before undertaking a reverse flip, and where do they most underestimate the cost or time involved?
Vinayak Burman: From a legal and regulatory perspective, a reverse flip is not merely a change in the place of incorporation of a company. Depending on the structure adopted, it may involve a cross-border merger, corporate restructuring or other reorganisation, each of which can trigger a range of corporate, foreign exchange, tax, valuation and regulatory considerations.
In India, Section 234 of the Companies Act, 2013, read with the applicable rules, provides the statutory framework for cross-border mergers, alongside the regulations and directions issued by the Reserve Bank of India. Accordingly, the proposed structure must be evaluated not only from a corporate law perspective but also from the standpoint of FEMA, valuation requirements, tax implications and applicable regulatory approvals.
The implementation also requires careful consideration of the transfer and continuity of intellectual property, contractual arrangements, licences and permits, employee equity and incentive arrangements, and other assets and obligations across jurisdictions. Existing shareholder rights, securities issuances and historical cross-border transactions may also require review to ensure that the proposed restructuring does not create regulatory or title-related issues.
One of the aspects most frequently underestimated is the extent of legal and regulatory diligence required on the existing overseas structure and its historical transactions. Before implementing a reverse flip, it is important to establish a clear and defensible record of the foreign entity’s incorporation, capitalization, securities issuances, shareholder arrangements, IP ownership, contracts and prior cross-border transactions. Early planning is therefore critical, particularly where multiple regulators and jurisdictions are involved.
ESOP liquidity programmes must balance employee benefits and IPO compliance
StartupTalky: ESOPs are often the first real liquidity event for startup employees. How should companies design ESOP buyback or liquidity programmes so they are fair to employees and legally sound, and still acceptable to SEBI when the company files its DRHP?
Vinayak Burman: ESOP liquidity programmes require a careful balance between providing meaningful liquidity to employees and ensuring that the programme is legally compliant, consistently administered and capable of withstanding scrutiny in the IPO process.
From a legal perspective, the starting point should be a clearly documented ESOP framework that sets out the eligibility criteria, vesting and exercise mechanics, treatment of vested and unvested options, pricing methodology, tax implications and the circumstances in which liquidity may be offered. Any buyback or secondary liquidity programme should be implemented pursuant to a transparent and objective framework, rather than through employee-specific or ad hoc arrangements.
Companies should also be particularly careful about the source of liquidity and the legal mechanism through which it is provided. Depending on the structure, there can be implications under the Companies Act, applicable SEBI regulations, foreign exchange laws where overseas employees or shareholders are involved, and tax laws. The company should ensure that the programme is properly authorised, documented and reflected consistently in its statutory records, cap table and financial statements.
From an IPO perspective, the objective should be to ensure that there are no surprises when the DRHP is prepared. Historical grants, exercises, cancellations, lapses, transfers and liquidity transactions should be capable of being fully reconciled and appropriately disclosed. Any employee liquidity programme undertaken close to the IPO should also be evaluated carefully to ensure that it does not create questions around preferential treatment, valuation, related-party considerations or the manner in which securities have historically been issued and dealt with.
Public listings require a shift toward institutional governance
StartupTalky: Listing obligations bring independent directors, related-party scrutiny and disclosure requirements. From your experience, which of these do founder-led companies find hardest to adapt to culturally, not just legally?
Vinayak Burman: The most significant cultural shift for founder-led companies is not necessarily the introduction of independent directors or the additional disclosure requirements in isolation. It is the transition from a founder-centric decision-making model to a governance framework where decisions must be capable of being independently evaluated, documented and explained to shareholders and the market. Independent directors can be particularly significant in this regard. Founders who have historically been accustomed to taking decisions quickly, based on their understanding of the business and long-standing relationships, need to become comfortable with independent directors asking difficult questions, seeking additional information and, where appropriate, disagreeing with management. The board has to function as a board of a public company, rather than simply as an extension of the promoter group.
Related-party transactions can present a similar cultural challenge. In a closely held business, transactions with promoter- or founder-related entities may have historically been viewed as commercially convenient or entirely routine. Once the company is listed, however, the focus shifts to transparency, arm’s-length principles, approvals, documentation and demonstrating that the transaction is in the interests of the company and its shareholders as a whole.
Ultimately, the challenge is to move from ‘we know why this decision makes sense’ to ‘we can demonstrate why this decision is appropriate, independently and transparently.’ Companies that begin making this transition well before the IPO generally find the listing process significantly smoother. IPO readiness, therefore, is as much about changing governance behaviour and institutionalising decision-making as it is about satisfying a checklist of legal and regulatory requirements.
An IPO changes a founder’s relationship with control and ownership
StartupTalky: Through The Lifeboat you have had candid conversations with founders about identity and entrepreneurship. What have those conversations taught you about the personal side of a founder deciding to take their company public and give up a degree of control?
Vinayak Burman: Through my conversations with founders on The Lifeboat, one thing that has become increasingly clear to me is that an IPO is not simply a financial or corporate milestone. For many founders, it is a deeply personal transition.
Founders spend years building a company around their vision, values and instincts. In the early years, they are often the ultimate decision-maker and the company can feel like an extension of their own identity. Going public changes that relationship. The company increasingly belongs not just to the founder and the early investors, but to a much broader group of public shareholders. The difficult part is therefore not necessarily ‘giving up control’ in a legal sense. It is learning to accept that control is being replaced by stewardship.
I have also found that founders who approach an IPO purely as a liquidity event can sometimes underestimate this transition. The more constructive mindset is to see the IPO as the point at which the founder’s role evolves—from being the person who controls the company to being the person responsible for building a company that can operate successfully beyond the founder.
Ultimately, the most successful transitions are those where founders recognise that they are not losing their identity or their entrepreneurial legacy; they are institutionalising it. The real question is not how much control a founder is giving up, but what they are building that is bigger than their own control.
 Apoorva Bajj